Quick answer
A shorter term means higher repayments but usually a lower total cost; a longer term means lower repayments but usually more cost overall and more time exposed to risk. The best term roughly matches how long the thing you're funding will keep earning for the business. Equipment, vehicles and premises can justify longer terms; stock, marketing and cash flow gaps should be repaid quickly.
Key points
- Match the term to the useful life of what you're funding.
- Shorter: higher repayments, lower total cost.
- Longer: lower repayments, higher total cost, more time at risk.
- Balloons lower repayments but push cost to the end.
- Short terms suit
- Stock, marketing, cash flow gaps
- Medium terms suit
- Vehicles, equipment, fit-outs
- Long terms suit
- Premises, acquisitions
- Rule of thumb
- Don't outlast the benefit
The term is the dial most owners turn to make a loan affordable. Stretch it and the repayments fall. But every extra month has a cost, and a term that outlasts what it funded leaves you paying for something long gone. This page compares short and long terms and offers a simple way to choose.
How do short and long terms compare?
| Shorter term | Longer term | |
|---|---|---|
| Regular repayment | Higher | Lower |
| Total cost in dollars | Usually lower | Usually higher |
| Pressure on cash flow | More | Less |
| Time exposed to risk | Less | More |
| Debt-free sooner | Yes | No |
| Flexibility for future borrowing | Frees up capacity sooner | Ties up capacity longer |
How do you choose the right term?
Start from what you’re funding:
| What you’re funding | Term that usually makes sense |
|---|---|
| Stock that sells within months | Very short |
| Marketing campaign | Short |
| Cash flow gap or tax bill | Short, or a flexible facility |
| Computers and technology | Short to medium |
| Vehicles | Medium |
| Machinery and equipment | Medium, within working life |
| Fit-out | Medium, within the lease term |
| Commercial premises | Long |
| Buying a business | Medium to long |
Then check the repayment against your quietest month. If it doesn’t fit, look at a slightly longer term, a smaller amount or a flexible structure, in that order.
The two mistakes to avoid
- Too short. Repayments squeeze cash flow, the business strains, and you may need to refinance at extra cost.
- Too long. You pay more in total and may still owe money after the asset is worn out or the benefit has gone.
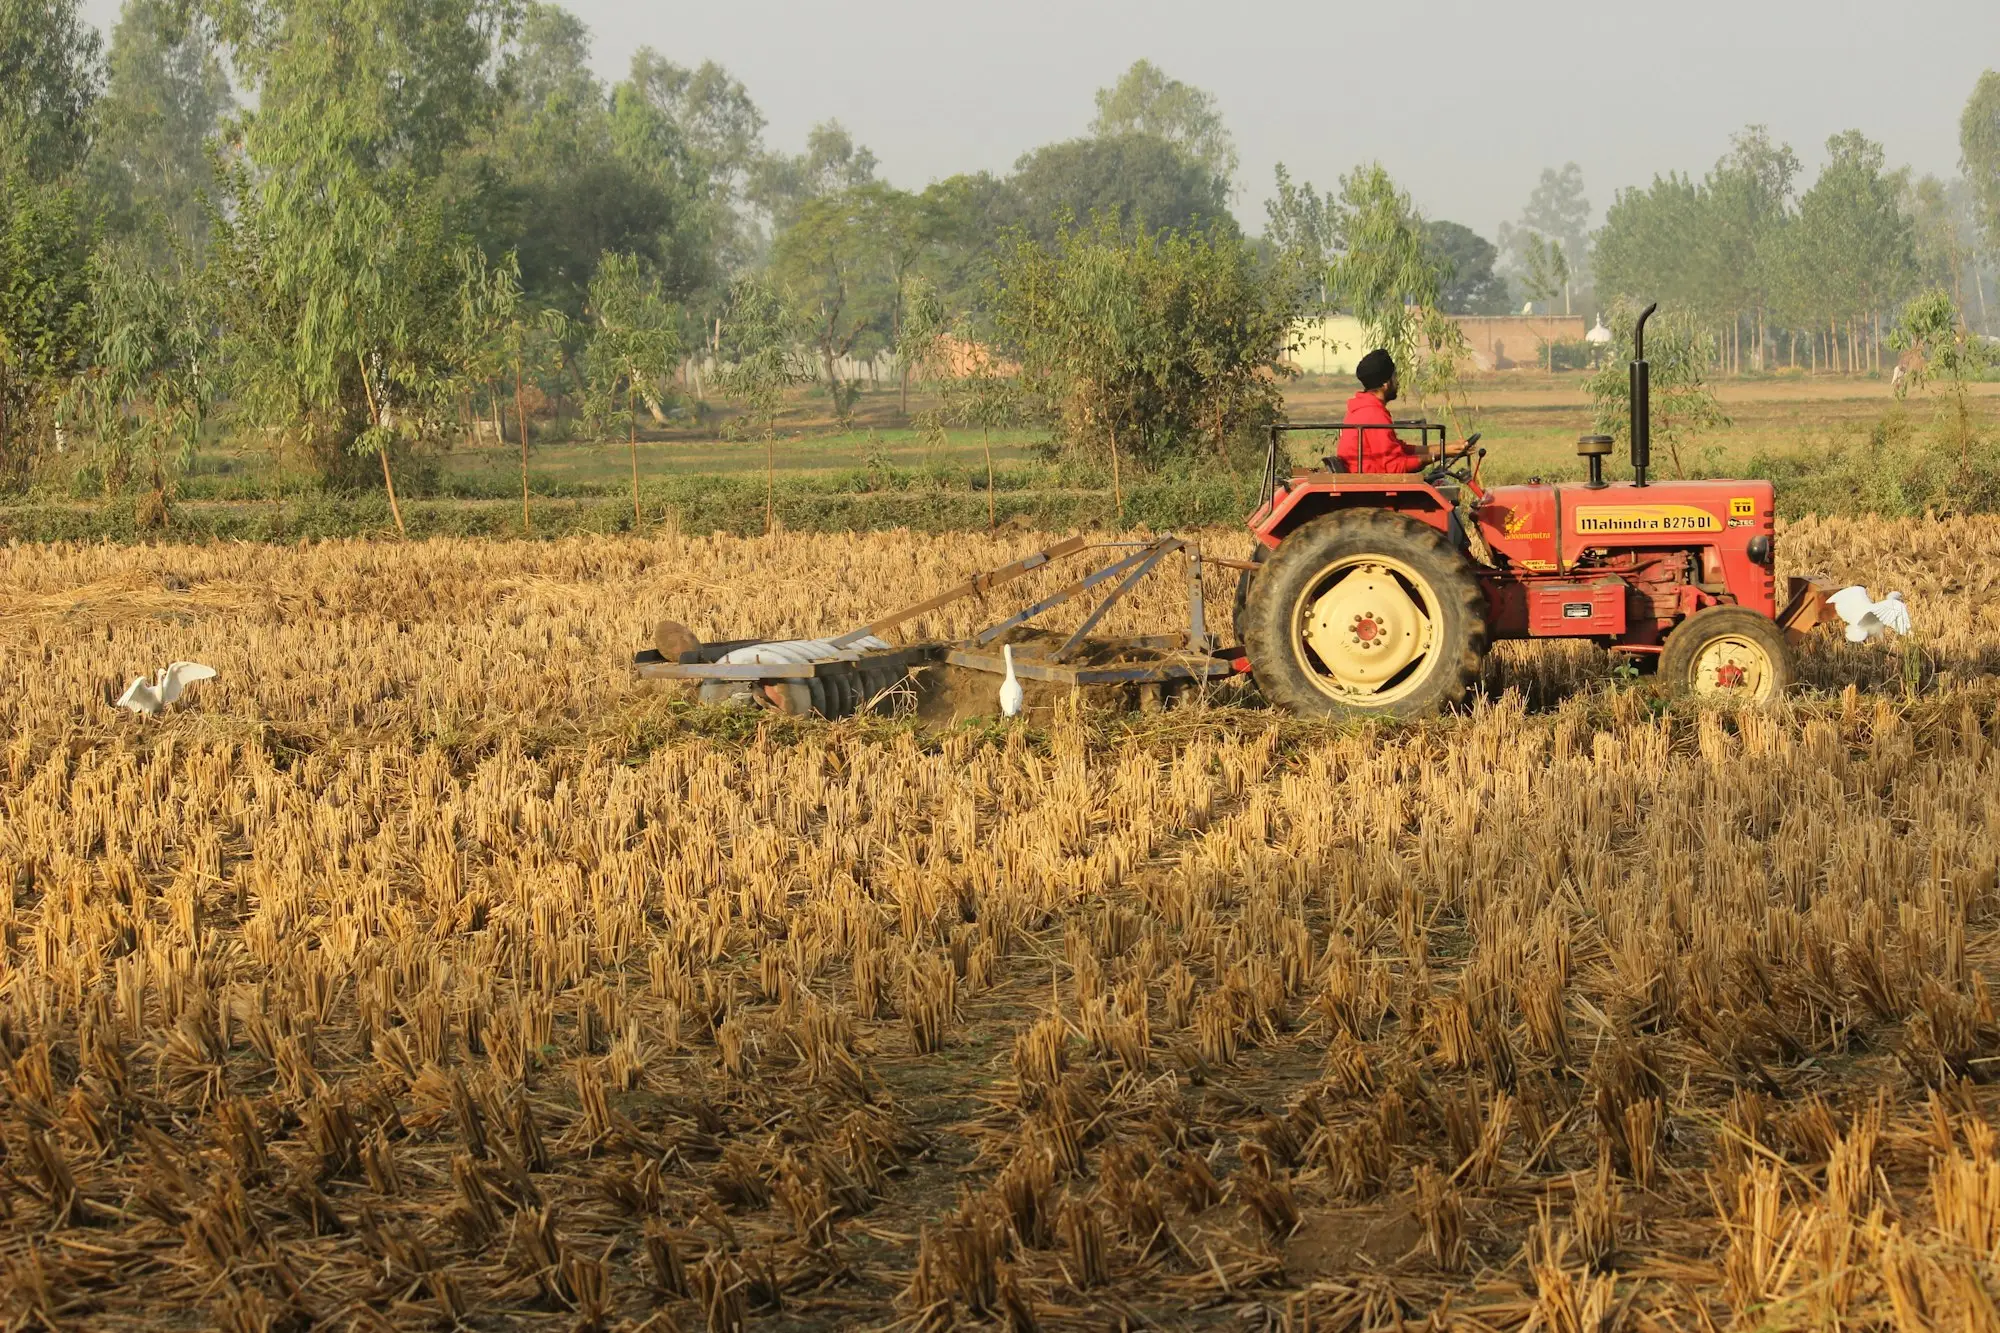
Illustrative example. A Wagga Wagga farm contractor is buying a $160,000 tractor he expects to run for eight years. A three-year term would push monthly repayments beyond what the off-season can carry. A seven-year term keeps repayments very low but would cost the most overall. He chooses five years with a modest balloon, keeping repayments manageable, the total cost reasonable and the tractor worth well more than the balloon when it falls due.
What about balloons and interest-only periods?
Both lower repayments now in exchange for more later:
- A balloon leaves a lump sum owing at the end. It suits assets with strong resale value, as long as you plan how to pay it.
- An interest-only period delays principal repayments. It suits projects that take time to produce income.
Include either in the total cost when comparing.
How does term interact with early payout?
A longer term with free early repayment can be a sensible safety net: low required repayments, but the option to pay faster in good months. A longer term with heavy break costs removes that option. Check the early payout terms before relying on paying it off sooner.
How do you test whether a term is too long?
A quick check uses three numbers: the loan term, the useful life of what you’re funding and, for assets, what it will be worth along the way.
- Write down the useful life. How long will this keep earning for the business? Be honest; most owners overestimate.
- Compare it with the term. The term should finish comfortably before the useful life ends.
- For assets, compare value with balance. At the halfway point, will the asset be worth more than what’s still owing? If not, you’d be stuck with negative equity if you needed to sell.
| Purpose | Honest useful life | A term that would be too long |
|---|---|---|
| Laptops and phones | 2 to 4 years | 5 years |
| Delivery van, high kilometres | 4 to 6 years | 7 years |
| Commercial kitchen equipment | 7 to 10 years | 12 years |
| Shop fit-out | The lease term | Longer than the lease |
| Marketing campaign | Months | Years |
A term that passes this test and still produces a repayment you can carry in a slow month is usually a good term. If no term passes both tests, the amount may be too large for the purpose, or a different structure, such as a line of credit, may fit better.
Find a term that fits what you’re funding
Tell us what the money is for and we’ll suggest terms that match its life. Asking doesn’t put a mark on your credit file; a check only comes up once you decide to go ahead. We don’t push your enquiry to a crowd of lenders. A real person compares a shorter and a longer option in dollars, so you can see exactly what the extra months cost.
Please be accurate on the form about the purpose and amount. Start your enquiry, or compare two terms side by side in the loan offer comparer and then check your options.
Frequently asked questions
Is a longer loan term always more expensive?
Usually, in total dollars, because you're paying for the money for longer. But the lower repayments can make it the safer choice for cash flow.
Can I repay a long-term loan early?
Often, but check the early payout terms. Some loans charge break costs or keep most of the fees regardless.
How long should equipment finance run?
Within the equipment's working life. A machine you'll replace in five years shouldn't be on a seven-year loan.
What is an interest-only period?
A period where you pay only interest, not principal. It keeps early repayments low but means more to repay later. It can suit a project that takes time to generate income.
Should a balloon be included?
Only if you're confident the asset will be worth at least the balloon at the end, or you'll have the cash to pay it.